Iowa’s Twenty, Forty and Fifteen Thousand Minimums
Dreaming of cruising down an Iowa gravel road on your ATV or UTV? Many of us picture the open air, the scenic routes, and the sheer freedom of it all. But before you hit the throttle on public roads, there's a crucial step that often causes confusion and frustration for riders: understanding Iowa's mandatory insurance requirements. This guide will meticulously break down the "20/40/15" minimums, explaining exactly what they mean for you and your machine, and why they're non-negotiable for anyone venturing onto Iowa's road system.
Understanding Iowa's Road Riding Insurance Mandate
It’s a common misconception that if your ATV or UTV is just for off-road fun, you don't need insurance. And that's often true for purely private land use. However, the moment your tires touch a public road, even a dusty gravel lane, the rules change dramatically. Iowa wants to ensure that anyone operating a powerful vehicle on public thoroughfares is financially prepared for potential accidents, protecting both you and other road users. This isn't about penalizing riders; it's about common-sense responsibility in a shared space.
Why Insurance is Non-Negotiable for Road Use
Think about the risks involved when you take your ATV or UTV out of the woods and onto a county road. You’re sharing the asphalt or gravel with cars, trucks, farm machinery, and even pedestrians or cyclists. Accidents, unfortunately, happen. A momentary lapse in judgment, an unexpected obstacle, or even another driver's mistake can lead to a collision. If you're involved in an incident and cause injury or property damage, the costs can be astronomical. Without insurance, you'd be personally liable for every penny, potentially leading to devastating financial consequences. Iowa's requirement for liability insurance is there to create a safety net, ensuring that injured parties can receive compensation and that you aren't left facing financial ruin. It's a standard practice for any vehicle capable of operating on public roads, from your daily driver to your off-highway vehicle.
Decoding the "20/40/15" Numbers
So, you've heard these numbers thrown around: 20/40/15. They might sound like some secret code, but they are actually the standard shorthand for Iowa's minimum liability insurance coverage requirements. These figures represent dollar amounts, specifically in thousands, that your policy must cover for different aspects of an accident involving bodily injury and property damage. Without diving into the deep legal jargon, it's essentially saying: this is the bare minimum financial protection you need to have in place. Many states use a similar numbering system, so if you've ever insured a car, these figures will look familiar. They're designed to provide a foundational level of protection, acknowledging that while accidents are rare, their impact can be profound.
Who Needs This Coverage
Let's be crystal clear: if you plan to operate your ATV or UTV on any public road in Iowa, you need this insurance. This includes those picturesque gravel roads, authorized paved secondary roads, and even crossing a highway at an intersection. It doesn't matter if you're just traveling a couple of miles to a friend's house, heading to a gas station, or taking the [Most Direct Route to an Iowa OHV Park]. The moment your tires leave private property and enter public access, the insurance mandate kicks in. This rule applies regardless of your residency; if you're riding in Iowa, whether you're a local or a visitor, you must comply. The only exceptions are generally for machines used strictly as "implements of husbandry" and operating within specific agricultural parameters, but even those have strict limitations on public road use. [Iowa ATV Insurance Requirement] is a fundamental piece of the puzzle for legal road riding.
Breaking Down Each Minimum Coverage Requirement
It's easy to see "20/40/15" and just nod, thinking "okay, I need insurance." But truly understanding what each number means empowers you to make informed decisions and appreciate the protection it offers. Each figure addresses a different aspect of the potential harm an accident can cause, ensuring that a comprehensive, albeit minimum, level of financial responsibility is in place.
The "Twenty Thousand" for Bodily Injury Per Person
The "20" in "20/40/15" stands for $20,000 in bodily injury liability coverage per person. This means that if you are at fault in an accident and one individual is injured, your insurance policy will pay up to $20,000 for their medical expenses, lost wages, pain and suffering, and other related costs. Imagine you're on a county road and, due to a blind spot, you accidentally clip the fender of a passing car, causing the passenger to suffer a whiplash injury requiring emergency room visits and physical therapy. Your insurance would step in to cover those costs for that injured passenger, up to that $20,000 limit. This is about providing immediate financial relief to an individual who has been harmed, ensuring they can access necessary care without being immediately burdened by crushing medical bills.
The "Forty Thousand" for Bodily Injury Per Accident
The "40" refers to $40,000 in bodily injury liability coverage per accident. This is the maximum amount your insurance will pay out for all bodily injuries combined in a single incident, no matter how many people are hurt. Let's revisit that hypothetical accident. If, instead of just one passenger, there were two injured individuals in the other vehicle, and their combined medical bills and lost wages exceeded $20,000 each, your policy would still cap the total payout for bodily injuries at $40,000. So, if one person had $25,000 in damages and the other had $20,000, your policy would pay $20,000 to the first person (due to the "per person" limit) and $20,000 to the second person, maxing out at $40,000. Any remaining costs would then fall back to you, the at-fault driver. This limit ensures there's a cap on your insurer's exposure while still providing substantial coverage for multiple victims. [Iowa ATV Insurance Minimum Coverage] clearly spells out these thresholds.
The "Fifteen Thousand" for Property Damage
Finally, the "15" in "20/40/15" represents $15,000 in property damage liability coverage per accident. This portion of your policy covers the costs to repair or replace property that you damage in an at-fault accident. This could be anything from another vehicle's bumper to a farmer's fence post, a mailbox, or even damage to the road itself. If your ATV veers off a [Unpaved County Secondary Roads in Iowa] and takes out a section of a farmer's wooden fence, your insurance would cover the cost to repair or replace that fence, up to $15,000. While $15,000 might seem like a lot, consider the cost of repairing modern vehicles, especially if a full body shop repair is needed, or the price of replacing specialized farm equipment. It's a significant amount, but in severe cases, it can still be exceeded.
Practicalities of Securing Your Iowa ATV/UTV Insurance
Getting the right insurance shouldn't be a headache, but it can feel like one if you don't know where to start. Many mainstream insurance providers offer policies for off-highway vehicles, and understanding what to look for can save you time and ensure you're adequately covered.
Finding an Insurer for Off-Highway Vehicles
The good news is that most major insurance carriers that provide auto insurance also offer coverage for ATVs and UTVs. Companies like Progressive, GEICO, State Farm, Allstate, and many regional providers are common places to start your search. It’s always a good idea to check with your existing auto or home insurance provider first, as they often offer multi-policy discounts, which can save you a bit of money. Some specialized carriers also exist for recreational vehicles. Don't be afraid to shop around and get multiple quotes. Look for providers who understand the unique aspects of off-road vehicle use, even if your primary intent is road use. When you're adding aftermarket parts, like those from SuperATV, you'll want to ensure your policy can be tailored to cover these additions, especially if they significantly increase the value of your machine. A standard liability policy won't automatically cover your custom winch or specialized suspension.
What Your Insurance Provider Will Ask You
When you call an insurance agent or fill out an online quote form, be prepared to provide some detailed information about yourself and your machine. They'll typically ask for your personal details (name, address, date of birth), your driving history (tickets, accidents), and specific information about your ATV or UTV. This includes the year, make, model, vehicle identification number (VIN), engine size, and any modifications or accessories that might affect its value. If you've invested in a quality lift kit or heavy-duty axles from SuperATV, be sure to mention these, as they contribute to the machine's overall worth and should be factored into your coverage. They'll also ask about how you plan to use the machine – primarily off-road, some road use, or primarily for utility/farm work. Be honest and clear about your intentions to ensure you get appropriate coverage.
Understanding Your Policy and Proof of Coverage
Once you've secured a policy, take the time to read through it carefully. Understand your coverage limits, deductibles, and any exclusions. It's crucial to know exactly what you're covered for. Your insurer will provide you with an insurance card or declaration page, which serves as your proof of financial responsibility. When riding your ATV or UTV on public roads in Iowa, you are legally required to carry this proof with you, just as you would in your car. A physical card or an electronic version on your phone is usually acceptable. During a roadside stop, a deputy will almost certainly ask for your [Iowa Driver's License Rules for ATVs] and proof of insurance. Not having it on hand can lead to unnecessary delays or even a citation, even if you are technically insured.
The Serious Consequences of Uninsured Road Riding in Iowa
While the desire to save a few bucks on insurance might be tempting, the potential costs of riding uninsured on Iowa's public roads far outweigh any perceived savings. The state takes these requirements seriously, and the penalties, both financial and legal, can be severe.
Financial Ramifications of an Accident Without Insurance
Imagine the worst-case scenario: you cause an accident with your ATV or UTV on a public road, and you don't have insurance. All those "20/40/15" limits we just discussed? They become your personal burden. If someone is severely injured, their medical bills could easily climb into the tens or even hundreds of thousands of dollars. Property damage to a newer vehicle could be substantial. Without insurance, you are personally responsible for every penny of those damages. This means lawsuits, garnished wages, liens on your property, and potentially years of financial struggle. Your personal assets – your savings, your home, your future earnings – could all be at risk. This isn't just a minor inconvenience; it's a life-altering financial catastrophe that can be avoided with a simple insurance policy.
Legal Penalties and Fines for Riding Uninsured
Beyond the crushing financial liability, Iowa imposes direct legal penalties for operating an ATV or UTV on public roads without the required insurance. You could be pulled over by a county sheriff's deputy or an Iowa DNR conservation officer and immediately cited. The exact fine can vary, but Iowa does have specific penalties in place. For instance, [Iowa Fines for No Proof of Insurance] can quickly put a dent in your wallet. Repeat offenses often carry escalating fines and could even lead to suspension of your driving privileges. It’s not just a warning; it’s a direct consequence of failing to comply with state law. These penalties are designed to deter uninsured riding and reinforce the importance of financial responsibility.
Roadside Stops and Proving Your Coverage
When you're out riding on Iowa's [Gravel Roads You May Ride Without Asking Anyone], you might encounter a law enforcement officer. If they pull you over, one of the first things they'll ask for, after your driver's license, is your proof of insurance. It's an automatic check, just like when you're driving your car. If you can't produce a valid insurance card or electronic proof, you're immediately in violation of the law. Even if you're insured but forgot your card, it can still lead to a citation and the hassle of having to prove your coverage later in court. Always keep your physical insurance card on your person or in a waterproof pouch on your machine, or ensure you have easy digital access on your phone. A deputy isn't going to simply take your word for it; they need to see the verifiable proof right there.
Here's a quick summary of Iowa's minimum liability insurance:
| Coverage Type | Per Person Limit | Per Accident Limit | What it Covers |
|---|---|---|---|
| Bodily Injury Liability | $20,000 | $40,000 | Medical expenses, lost wages, pain and suffering for injuries you cause to others. |
| Property Damage Liability | N/A | $15,000 | Repairs or replacement of property you damage belonging to others (vehicles, fences). |
Beyond the Minimums: Additional Coverage Considerations
While the "20/40/15" minimums are what Iowa legally requires for road use, they represent just the bare bones of protection. For many riders, especially those with significant investments in their machines, opting for additional coverage is a wise decision that offers greater peace of mind.
Why More Coverage Might Be a Smart Move
The "20/40/15" minimums might seem sufficient for minor fender-benders, but what if you're involved in a serious accident? Modern medical costs can quickly exceed $20,000 for a single injury, and the damage to newer vehicles can easily surpass $15,000. If your liability limits are exhausted, you're personally on the hook for the remaining balance. For example, if you cause $50,000 in bodily injury to one person, your minimum $20,000 coverage leaves you personally responsible for the other $30,000. Many financial experts recommend carrying higher liability limits, often $100,000/$300,000 bodily injury and $50,000 or even $100,000 property damage, to better protect your assets in catastrophic situations. This extra protection costs relatively little more compared to the immense financial risk it mitigates.
Exploring Optional Coverages
Beyond basic liability, insurance providers offer a range of optional coverages that can further protect your investment and yourself:
- Collision Coverage: This pays for damages to your ATV or UTV if it collides with another vehicle or object, or rolls over, regardless of who is at fault. This is particularly important if you have a loan on your machine or if it’s a high-value item.
- Comprehensive Coverage: This covers non-collision events, such as theft, vandalism, fire, natural disasters (like floods or hail), or damage from hitting an animal. If you park your machine at a trailhead and it's stolen, this coverage would help you replace it.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: This protects you if you're involved in an accident with another driver who doesn't have insurance or doesn't have enough insurance to cover your damages. While you're required to have insurance, not everyone on the road does.
- Accessory Coverage: If you've upgraded your machine with custom parts, a winch, a specialized lighting system, or premium tires from SuperATV, ensure your policy has adequate accessory coverage. Standard policies may only cover factory-installed parts.
- Roadside Assistance: Many policies offer this as an add-on, which can be invaluable if you break down far from home or a trailer.
These options add to your premium, but they provide a much broader safety net, protecting not just others, but also your own machine and financial well-being.
SuperATV and Protecting Your Investment
For many Iowa riders, their ATV or UTV is more than just a recreational vehicle; it's a significant investment, often customized with performance parts and accessories. Companies like SuperATV offer a vast array of aftermarket products, from heavy-duty axles and lift kits to windshields and plows, all designed to enhance your machine's capabilities and value. When you pour money into these upgrades, you need to ensure that your insurance policy reflects that increased value.
It's crucial to inform your insurance provider about any significant modifications or aftermarket accessories. Many standard ATV/UTV policies have limited coverage for accessories or may not cover them at all unless specifically added. Discussing your SuperATV winch, a custom full cab enclosure, or upgraded suspension with your agent is vital. This ensures that if your machine is damaged or stolen, you’re not left paying out of pocket to replace those valuable additions. Think of it as protecting the full value of your pride and joy, not just its stock price.
Navigating Iowa's Broader Road Use Rules for OHVs
Beyond insurance, several other critical rules govern ATV and UTV use on Iowa's public roads. Understanding these regulations is essential for legal and safe operation, preventing citations, and ensuring an enjoyable ride. The insurance requirement is just one piece of the puzzle; you must meet all conditions to be truly "street legal" in authorized areas.
Eligibility Requirements for Riding on Iowa Roads
Iowa has specific requirements for who can legally operate an ATV or UTV on public roads. First and foremost, the operator must be at least 18 years old. This isn't just a suggestion; it's a hard and fast rule. [Iowa Minimum Age to Ride a Road] is 18. Additionally, the operator must possess a valid driver's license. This means a standard automobile driver's license is sufficient; you don't need a special motorcycle endorsement or an ATV-specific license. However, if your driver's license is suspended or revoked for any reason, you cannot legally operate an OHV on a public road. These rules are in place to ensure that drivers have a certain level of maturity and understanding of road laws before sharing public spaces with other vehicles.
Essential Equipment for Road-Legal Operation
Transforming your off-road machine into a road-legal one isn't just about insurance; it also involves specific equipment requirements. Iowa mandates certain items to ensure visibility and safe operation:
- Headlights: Your ATV/UTV must have at least one headlight that meets visibility standards. And here's a crucial point: when riding on public roads in Iowa, your headlights must be on at all times, even during daylight hours.
- Taillights: At least one taillight, visible from the rear, is required.
- Brakes: Your machine must have a functional braking system.
- Muffler: An effective muffler system is required to keep noise levels within legal limits.
- Mirror: At least one rearview mirror is necessary, allowing the operator to see what's behind them. [Iowa Mirror Requirement for Road Use] helps in safe lane changes and monitoring traffic.
- Horn: A working horn is required for signaling and warning other road users. [Iowa Horn Requirement for Road Use] is a critical safety feature.
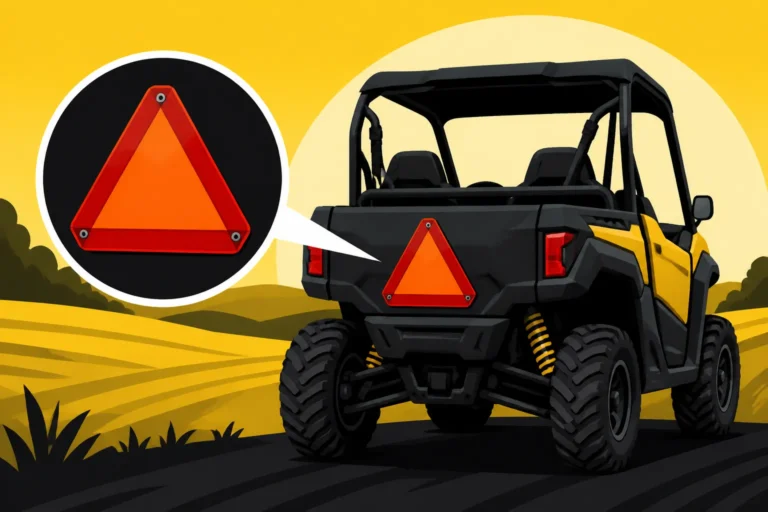
- Slow-Moving Vehicle (SMV) Triangle: Because ATVs and UTVs are typically slower than other road traffic, Iowa requires a red-orange reflective SMV triangle prominently displayed on the rear of the machine. This alerts other drivers to your slower speed. [Iowa Slow-Moving Vehicle Sign Rules] dictate its placement and visibility.
- Brake Lights and Turn Signals: While not always required for purely off-road machines, if you plan extensive road use, adding brake lights and turn signals can greatly enhance safety and communication with other drivers.
Always double-check that all your lights are working before you head out, and that your SMV triangle is clean and clearly visible.
Where You Can and Cannot Ride
Iowa's rules on where you can legally ride your ATV or UTV on public roads are quite specific and often misunderstood. Generally, ATVs and UTVs are permitted on [Unpaved County Secondary Roads in Iowa] (gravel roads) unless explicitly prohibited by a county ordinance. However, riding on paved county roads, state highways, or city streets is usually prohibited unless the specific county or city council has passed an ordinance authorizing such use.
- Paved Secondary Roads: Some counties have authorized certain paved secondary roads, but you'll need to check with the specific county's board of supervisors.
- City Streets: Similarly, cities like Waukon have passed ordinances opening certain streets to OHVs, but this is decided at the local level. You cannot assume a city's streets are open. [Are ATVs Street Legal in Iowa?] provides a detailed look at these nuances.
- Primary Highways (State Roads): Generally, ATVs and UTVs are not permitted on state highways or interstates, except for directly crossing at an intersection.
- Most Direct Route: Even when riding on authorized roads, you are typically restricted to taking the [Most Direct Route to an Iowa OHV Park] or other approved destination, or the most direct route home. Joyriding aimlessly on public roads is generally not permitted.
Before you venture out, always confirm the local ordinances for the specific county or city you plan to ride in. A quick call to the county auditor's office or city clerk can save you a lot of trouble.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.